5 Key Takeaways from This Article
| Country | Details |
|---|---|
 <a”>Bulgaria |
Corporate income tax is 10% and income tax is 10%. |
 Ireland |
Ireland applies a corporate income tax rate of 12.5% to qualifying trading income, while non-trading income, including most investment and rental income, is generally taxed at 25%. In addition, Ireland has implemented the OECD Pillar Two global minimum taxation rules, which require qualifying multinational enterprise groups and large domestic groups with consolidated annual revenue of at least EUR 750 million to be subject to a minimum effective tax rate of 15%, calculated under the applicable rules. Ireland remains an important European location for international businesses, but its taxation framework must be assessed according to the nature of the company’s income, corporate structure and eligibility for applicable reliefs. |
 Cyprus |
Cyprus increased its standard corporate income tax rate from 12.5% to 15%, effective from 1 January 2026, as part of a comprehensive tax reform. Cyprus continues to provide specific tax incentives and exemptions, including the intellectual property box regime, participation exemptions and tax benefits available to qualifying individuals and businesses. The availability of these incentives depends on statutory eligibility conditions, the nature of the income and the company’s economic activities. Corporate tax residence, effective management and applicable international tax rules must also be considered. |
 Estonia |
Estonia operates a corporate income tax system under which retained and reinvested profits are generally not taxed until distribution. Since 1 January 2025, distributed corporate profits have been subject to income tax at a rate of 22/78 of the net distribution, equivalent to 22% of the gross profit. The standard personal income tax rate is also 22% in 2026. Corporate income tax may additionally arise on certain non-business expenses, fringe benefits, gifts, donations and other taxable payments, even where no dividends are distributed. |
Things to Consider While Establishing a Company in Europe
One has to consider the overall tax burden that is other than corporate tax, which includes VAT, labour taxes, and social contributions.
Double Taxation: You have to see the double taxation treaties between your country and the country in which you plan to invest and start a business.
Country reputation: Some of the low-tax countries are considered – though this is a misconception – as “tax havens”, which affects reputation and consequently follow-on business behaviour.
You should, therefore, always carry out the proper analysis and, when required and relevant, consult professional tax and legal advisors prior to decisions about registering a business or investing in any jurisdiction.
European countries with highest % of foreign ownership of firms
Data relating to foreign firm ownership in European countries fluctuate over time and depend on a set of factors such as economic policies, investment climate, and global trends. However, according to historical data and economic reports, some European countries have traditionally reported high percentages of foreign firm ownership. Examples include:

1. Luxembourg
Luxembourg is a large financial centre with a friendly tax policy and pronounced international orientation; accordingly, the proportion of foreign-owned companies in the country is very significant.

2. Netherlands
Thanks to a stable economic position, convenient location, and encouraging investment climate, the country has gained for many years a long-standing reputation as a recipient of foreign investment.
3. Switzerland
Switzerland offers a stable political environment, along with a tax-friendly climate and in addition provides complete confidentiality to foreign companies.
4. UK
UK, London is a global financial hub and has historical exposure to foreign investments.
5. Ireland
Ireland remains one of the favourite destinations for global headquarters and foreign firms; mainly it is because of the tax rate of.

Estonia
The Estonian e-Residency program, for example, has been a real magnet for foreign investments, more than 15% of the companies created by foreign non-Estonians and more than 200 mln euros in taxes received last year.
What to consider for non-dom status persons
- Foreign ownership of companies’ shares may increase or decrease as political and economic events will appear, among which may be Brexit, any new changes to tax legislation and international agreements.
- Market dynamics: Global economic trends, such as trade wars, pandemics, and financial crises, can also impact a country’s attractiveness for foreign investment.
- Please refer to recent economic reports, statistics, and analyses for the most up-to-date information and a more detailed understanding.
Lowest corporate tax in Europe
Tax obligations in European countries depend on the taxpayer’s residence status, the source of income, applicable domestic legislation and relevant international tax treaties. Individual tax residents are generally subject to taxation on their worldwide income, while non-residents are usually taxed on income arising from sources within the relevant jurisdiction. However, tax residency is not determined exclusively by the number of days spent in a country. Many European jurisdictions apply a 183-day presence test alongside other criteria, including permanent accommodation, habitual residence, centre of vital interests and economic connections. The exact conditions differ between countries, and double taxation agreements may contain tie-breaker rules for individuals qualifying as tax residents in more than one jurisdiction. The quirk in the EU law is that, within the bloc, each state has a right to set the amount of rates as it sees fit. Citizens of European countries can take advantage of a double taxation treaty if the jurisdictions of one’s citizenship and residence have concluded a double taxation treaty.
Taxation within the European Union is governed by a combination of national legislation and harmonised EU rules. Although Member States generally retain authority over their corporate and personal income tax rates, EU legislation establishes common requirements in areas such as VAT, administrative cooperation, anti-tax avoidance measures and minimum taxation for large corporate groups. Council Directive (EU) 2022/2523 introduced a framework for a minimum effective tax rate of 15% for qualifying multinational enterprise groups and large domestic groups with annual consolidated revenue of at least EUR 750 million. This article examines European taxation in 2026, including corporate income tax, personal income tax, VAT, social security contributions and the requirements for obtaining tax residency.
Types of Taxes in European Nations
Europe uses myriad taxes that are different and dependent on the government of each jurisdiction. Sometimes, the minimum rate is normally imposed by the EU legislation, for example, excise duties. Tax obligations depend on the status of a person and where their income originates.
- Corporate Taxes: Every company has to pay its taxes directly to the regulatory authority of their own country where the business is being carried out. However, individual payments are allowed, but in most cases employers take the responsibility for the payment of taxes of employees.
- Tax Structures: The countries may have either a progressive or stable tax system.
Critical Types of Taxes in the EU
Both citizens and foreign residents are subject to various types of taxes in European countries, including:
Income Taxes for Individuals
The income tax can be imposed by a country where an individual obtains an income or holds a tax residency. This encompasses wages, pensions, allowances, profits from property, and capital gains. A foreigner employed in an EU state who has a salary and does not obtain tax residency will only be required to pay the local income tax on a salary that was obtained within that particular country but not that earned outside. Tax residents, however, pay on worldwide income.
Corporate Taxes
All businesses will need to pay a tax in the state in which they are both registered and operate. The rules of taxation differ depending on the jurisdiction, as there are resident companies which get taxed both on national and international level while foreign businesses are to be taxed only based on local activities.
VAT
EU law provides a minimum standard VAT rate of 15%, a minimum reduced rate of 5%. The appropriate rate of VAT, which is incorporated into the price, is decided by the individual states and businesses can deduct pre-paid VAT on sales.
Harmonized Excise Duties
Excise duties are indirect taxes by consumers of certain products, such as spirits, tobacco, and electricity. The EU sets minimum rates, but member states can set higher rates.
Social Levies
Social taxes by employees, employers, and the self-employed pay for benefits such as pensions and sickness allowances. Even though there is no uniform amount in Europe for social levies, usually a person is subject to social security contributions in the country where he or she works. EU citizens who have acquired benefits may continue to receive them even after re-domiciling to another member state.
Please note that additional fees may apply.
In some countries, residents are liable to pay additional fees, such as environmental or transport taxes, which are typically the responsibility of vehicle owners. Furthermore, citizens in countries such as Austria, Germany, and Finland may be required to pay church taxes if they are registered members of a religious institution.
Taxation of Individuals
Residency will be considered if a person has remained in the jurisdiction for at least six months in the previous year. Or residency may be held based upon permanent address or the situs of their interests. Many EU and non-EU jurisdictions have double taxation treaties to prevent income from being taxed in a large number of countries.
The following classes of income are liable to taxation:
By EU law, individuals are required to pay tax on the following classes of income, including:
- Salary: In the majority of the EU member states, income tax on wages is progressive. The lowest rate – 10% – is levied in Bulgaria and Romania, while in Finland, the highest rate can be as much as 56.5%. Payment is normally by deduction at source, responsibility usually lying with the employer.
- Taxation on property, inheritance, and gifts: Taxes could be levied on nearly any form of asset, such as animals and cryptocurrency to vehicles. This is not a practice used by every country in the world, and even among the ones using it, progressive rates are often set. Bulgaria is at a minimum of 0.4%, while Spain goes up to 87.6% depending on the region.
- Dividends: The minimum is Greece, going to a maximum of 42% in Denmark. The dividend tax is payable by the individual.
- Capital Gains: The taxation rate of capital gains varies in each country. The lowest ones are 15%, recorded in Greece and Hungary, up to a maximum of 42% in Denmark.
A foreign company registered in a European country has an obligation to pay taxes both on domestic and international profits. On the other hand, companies of foreign origin are liable to pay taxes only on local income. Fees payable by legal entities include:
Corporate Income Taxes:
These vary from the lowest 9% in Hungary to the highest 25% in France. In addition is the VAT ranging from country to country. The lowest is Luxembourg with a rate of 16% while the highest is Hungary with 27%. Lithuania has the lowest employer contribution rate, 1.77%, while Slovakia has the highest rate, 35.2%.
Customs Duties:
Companies in customs unions are exempted from customs duties, but businesses importing goods from outside the country are required to pay customs tariffs depending on the origin and value of the merchandise moved into their country.
Taxation of income produced by foreign branches
Most usually, such a foreign company branch, operating in Europe, is subject to corporate tax and VAT. For the dependent branches, one is allowed to consolidate their financial activity reporting, while independent branches have to create a separate report.
Cheapest corporation tax in Europe in 2025
When choosing a country to move to or start a company, foreigners often tend to choose jurisdictions with the most favourable taxation. The lowest income taxes in the EU states are presented in the table below:
Tax | Rate in % | Countries
Personal income tax | 10% | Bulgaria and Romania (standard rates, subject to applicable exemptions and special rules)
Corporate income tax | 9% | Hungary (standard national rate; local business tax and other obligations may apply)
Standard VAT | 17% | Luxembourg (lowest standard VAT rate in the European Union in 2026)
These figures represent selected statutory rates rather than the overall effective tax burden. Actual taxation depends on the nature of the income, available reliefs, social contributions, local taxes and other applicable legislation.
How to become a tax resident in an EU country
Tax residency is a legal status determined under the domestic tax legislation of the relevant jurisdiction and applicable international tax treaties. It is not necessarily dependent on obtaining citizenship, a passport or a residence permit. A person may become tax resident by satisfying statutory criteria such as habitual residence, physical presence, permanent accommodation or the location of their centre of vital interests. Conversely, holding a residence permit does not automatically establish tax residency. Individuals relocating to another European country should assess the tax implications of their personal circumstances, income sources and possible continuing tax obligations in their previous country of residence.
Lowest corporate tax in Europe
The people pay the most tax in Denmark, France and Austria; the lowest income tax rates in Europe are imposed in Hungary, Estonia and the Czech Republic.
Payment of taxes
Most European countries have introduced a progressive tax payment structure, i.e. the levies increase with the growth of wages. The rates and the number of categories vary greatly from country to country.
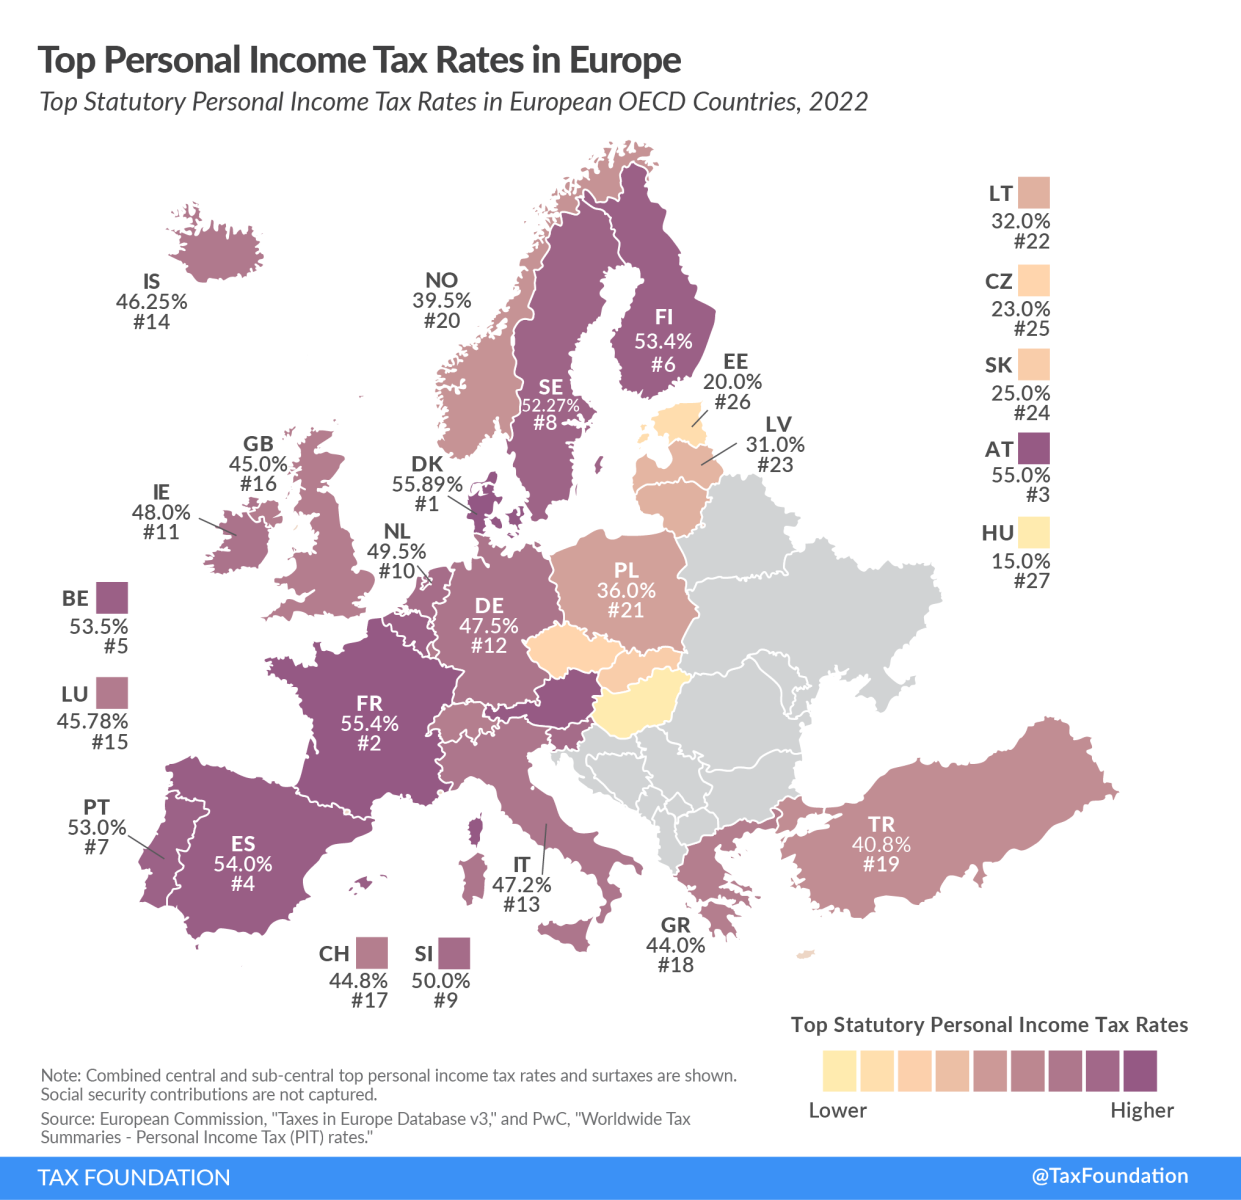
Income tax rates in Europe
The highest personal income tax rates among the Organisation for Economic Co-operation and Development (OECD) countries are imposed in Denmark – 55.9%, France – 55.4% and Austria – 55%.
In Spain this indicator is 54%, in Belgium – 53.5%. The maximum rates are very high in Finland, Portugal and Sweden.
| Country | Tax Rate |
 Denmark |
55.9% |
 France |
55.4% |
 Austria |
55% |
 Spain |
54% |
 Belgium |
53.5% |
 Finland |
53.4% |
 Portugal |
53% |
 Sweden |
52% |
 Slovenia |
50% |
Netherlands |
49.5% |
Ireland |
48% |
 Germany |
47.5% |
 Italy |
47.2% |
 Iceland |
46.3% |
Luxembourg |
45.8% |
 UK |
45% |
 Switzerland |
44.8% |
 Greece |
44% |
 Turkey |
40.8% |
 Norway |
39.5% |
 Poland |
36% |
 Lithuania |
32% |
 Latvia |
31% |
 Slovakia |
25% |
 Czech Republic |
23% |
 Estonia |
20% |
 Hungary |
15% |
Bulgaria |
10% |
Countries with low taxes Europe
Hungary has the lowest income tax rate in Europe—15%, Estonia has 20%, and the Czech Republic has 23%. Each country sets its own levies, but common standards must be fulfilled throughout the European Union. Social tax is a direct tax. Its purpose is to ensure that a socially insured person is entitled to receive certain services from the state.
Services may include the following:
- old-age pension
- a disability pension
- a survivor’s pension
- sick pay
- maternity benefits
- unemployment benefits
- funeral allowance
Therefore, accordingly, in social tax, the following payments for different purposes include: payment for accumulation of pensions, maternity benefits, sickness, disability, incapacity for work and unemployment benefits (insurance).
The taxpayers are employers, employees, self-employed persons, and persons who pay social tax at their own wish.
Wages will be the object of tax in view of the legislation, both for employees and employers, while a certain amount will present the object of tax for self-employed persons. Normally, the employer withholds a part of the tax—the part that the employee pays—from the wages and pays another part of the tax for the employer. Generally, social tax has to be paid once per month. In most countries, the amount of social tax must be decreased by the amount of personal income tax.
Or in other words, the more social tax paid, the higher the social security of the taxpayer; for example, the old-age pension depends on the amount of social tax paid.
The name of social tax is different in every country. For example, in the UK it is called “National Insurance,” in Ireland, “Pay Related Social Insurance (PRSI),” and in other countries, it is called “social insurance.”
The average social tax rate for the whole European Union is 34%. The tax rate is relatively low in Denmark due to its high personal income tax. Social tax in the Netherlands is integrated into income tax.
Table of social taxes for different European countries, showing the tax rate in per cent:
| № | Country | Tax rate (%) |
| 1 | Denmark |
14.00 |
| 2 | Ireland |
14.75 |
| 3 |  Malta |
20.00 |
| 4 | Luxembourg |
25.94 |
| 5 | Finland |
28.00 |
| 6 | Netherlands |
28.81 |
| 7 |  Croatia |
30.70 |
| 8 |  Lithuania |
30.98 |
| 9 | Bulgaria |
31.40 |
| 10 | Sweden |
31.42 |
| 11 | Austria |
32.00 |
| 12 | Estonia |
33.00 |
| 13 | Poland |
33.00 |
| 14 | Cyprus |
34.00 |
| 15 | Latvia |
34.09 |
| 16 | Portugal |
34.75 |
| 17 | Spain |
37.25 |
| 18 | Slovenia |
38.20 |
| 19 | Germany |
39.00 |
| 20 |  Romania |
39.95 |
| 21 | UK |
40.00 |
| 22 | Greece |
40.06 |
| 23 | Czech Republic |
45.00 |
| 24 | Hungary |
45.50 |
| 25 | Belgium |
48.07 |
| 26 | Slovakia |
48.60 |
| 27 | France |
50.00 |
| 28 | Italy |
50.00 |
These data highlight the diversity for social tax rates across European countries. The relatively low rates of Denmark and Ireland compare with the relatively high French and Italian rates.
Average salary in Europe 2023-2025
The following series of tables within the article on European Union taxation ranks European countries by average monthly salary once all taxes have been deducted. This figure represents the average net income received by employees. Yet, this is not very relevant because, in some countries, workers may get less take-home pay; yet, they will pay high taxes, which in turn may come back to them in the form of certain services from the state: free medicine, education, etc. In countries with liberal economies, income may be higher and taxes less. Nevertheless, citizens in these countries often pay a significant proportion of their income towards various goods and services that are free or highly subsidized in more socially sensitive economies. It must be emphasized that the current ranking of average wages takes into account only some of these factors. The numbers presented here reflect only the average nominal wage that the average citizen actually takes home – net pay. It is also to be taken into consideration that this ranking corresponds to the official net salary, and in some countries with a high level of shadow economy, real average salary can be higher.
The highest average incomes were recorded in Scandinavia and Switzerland, whereas the lowest salaries have been recorded in Eastern and South-Eastern European countries. Traditionally, the lowest salaries among EU countries have been those of Bulgaria and Romania.
Following is a list of European countries based on figures from the IMF, World Bank and national statistical agencies. All data are converted to euros at current exchange rates at time of publishing. Average salaries are given for both EU countries and other countries within Europe:
| № | Country | Average monthly salary, € |
| 1 | Switzerland |
4 902 |
| 2 | Denmark |
3 914 |
| 3 | Norway |
3 795 |
| 4 | Luxembourg |
3 573 |
| 5 | Iceland |
3 221 |
| 6 | Austria |
3 104 |
| 7 | Ireland |
3 041 |
| 8 | Germany |
2 970 |
| 9 | France |
2 791 |
| 10 | Sweden |
2 770 |
| 11 | Finland |
2 509 |
| 12 | UK |
2 454 |
| 13 | Belgium |
2 442 |
| 14 |  San Marino |
2 390 |
| 15 | Netherlands |
2 152 |
| 16 | Spain |
2 039 |
| 17 | Italy |
1 752 |
| 18 | Cyprus |
1 658 |
| 19 | Slovenia |
1 363 |
| 20 | Czech Republic |
1 250 |
| 21 | Estonia |
1 214 |
| 22 | Greece |
1 116 |
| 23 | Portugal |
1 110 |
| 24 |  Lithuania |
1 059 |
| 25 | Latvia |
1 050 |
| 26 |  Malta |
1 021 |
| 27 | Poland |
1 002 |
| 28 | Croatia |
974 |
| 29 | Hungary |
950 |
| 30 | Slovakia |
919 |
| 31 | Romania |
785 |
| 32 |  Montenegro |
706 |
| 33 | Bulgaria |
665 |
In Europe, CGT means the tax charged on any profit made from disposing of assets such as shares, bonds, or real estate. The rates and conditions vary from country to country, reflecting different national policies and economic strategies for EU countries. In certain European states, it emerges as one of the vital sources of revenue, whereas in others, it may be reduced or not applied at all in specific cases.
The countries that have the highest rates of taxation on capital gains include:
High Capital Gains Tax Rates: The country of Denmark has one of the highest capital gains tax rates in the world and may reach as high as over 40%, depending on the amount and kind of investment.
France has similarly high rates, especially if social contributions are included in calculating capital gains tax. In those cases, the overall liability can be more than 30%. Ireland: The capital gain tax rate can also be as high as 33%.
The lowest capital gains tax rates include:
Czech Republic: Because of special capital gains, it has a minimum or even no tax at all.
Slovakia provides relatively low rates with some possibilities for tax planning. The capital gains tax rate in Estonia is connected with the income tax rate of 20%. Part of the capital gains are not taxed at all.
Some of the following characteristics of Europe’s capital gains tax are:
- Holding period: In a number of countries, the taxation rate depends on the period an asset is held. Generally, a considerably reduced rate is given to investments held for an extremely long time.
- Incentives and Exemptions: Some states give incentives to small businesses and retired persons, and some on reinvestment of sale proceeds in certain types of assets.
Particularly when planning your personal tax strategy, remember the differences in tax systems and regulations that exist throughout Europe, even within the EU. Yet, importantly, capital gains are treated differently in a lot of the individual countries of the European Union. Therefore, investors and asset owners should consider local conditions and regulations of the countries in which they are investing or holding assets, taking into account.
Taxation of capital gains is a multi-faceted and complex field throughout Europe. An investor may either account for local conditions and regulations or seek opportunities to optimize the tax position while investing in or owning assets. Depending on the country, the investment size, and the investor’s particular circumstances, an effective tax strategy may significantly reduce the overall tax burden.
Lowest VAT in Europe 2023-2025
Some entrepreneurs do their tax planning based on VAT rates, so we summarized the relevant information in a table: It is necessary to underline that the VAT in EU member states and ———– in other European countries differs.
The critical difference is that the legislation of VAT in EU countries is harmonized in accordance with the EU VAT Directive 2006/112/EC of 28 November 2006. This directive is based on the following principles:
- Value-added tax is charged for transactions involving a VAT payer in the territory of a member state and on imports of goods into the territory of the EU. It is important to note, however, that the import of goods from one member state of the EU to another member state of the EU is subjected to VAT in the country where the goods will be used.
- Country of the purchaser shall be
considered
to be a place of supply of goods in case of intra-EU sales. Import VAT
becomes payable
in case of supplies from outside the EU in the country where goods have been cleared and released into free circulation. - The obligation to charge VAT arises when the purchaser receives the goods or services. A supplier’s issuing of an invoice does not constitute this moment.
- Under Council Directive 2006/112/EC, EU Member States must generally apply a standard VAT rate of at least 15%. As of 2026, Luxembourg has the lowest standard VAT rate in the European Union at 17%, while Hungary has the highest at 27%.
Following amendments introduced by Council Directive (EU) 2022/542, Member States may apply up to two reduced VAT rates of at least 5% to qualifying categories of goods and services listed in Annex III of the VAT Directive. Under specified conditions, Member States may also apply a reduced rate below 5% or an exemption with the right to deduct input VAT to a limited number of eligible categories.
The availability of reduced rates, super-reduced rates and exemptions depends on the applicable EU provisions and national legislation.
Your Europe
- The Directive provides for cases where certain goods and services are completely exempt from VAT. In general, any export from an EU country, irrespective of the destination, is refundable in respect of previously paid VAT connected with the production of goods sent for export.
- VAT refund in the EU-the most extensive clause of the Directive, which provides for the possibility to refund in the country of registration VAT that was paid in another EU member state.
- Since 1 July 2021, the European Union has applied harmonised VAT rules to cross-border business-to-consumer (B2C) distance sales of goods and certain digital services. A combined annual threshold of EUR 10,000 generally applies to qualifying cross-border B2C supplies made by businesses established in a single EU Member State. Once the threshold is exceeded, VAT is generally due in the Member State where the customer is located, subject to applicable rules and exceptions.
Businesses may use the EU One Stop Shop (OSS) scheme to declare and pay VAT due in other participating Member States through a single registration, rather than registering separately for VAT in each destination country. The former national distance-selling thresholds, including Belgium’s EUR 35,000 threshold, no longer apply under the current system.
Since 1 January 2025, eligible small businesses may also benefit from the cross-border VAT exemption scheme, subject to an EU-wide annual turnover ceiling of EUR 100,000 and applicable national thresholds.
- With the EU, you can check the VAT number of any European company. This can be done through a special service on the official website of the EU by selecting the country where you received the VAT number and entering that number.
- Value Added Tax Number – a unique number assigned to a legal entity when registering as a value added tax payer. In EU countries it starts with two letters of the country code, the remaining symbols are digits and the number of digits may vary from country to country.
Current value added tax (VAT) rates in European countries
| Country | EU membership | Basic rate of VAT | Reduced VAT rate | Minimum threshold for registration as a VAT payer |
|
Austria | Yes | 20% | 13%, 10%, 0% | Small business VAT exemption threshold of EUR 55,000 in annual turnover, applicable from 1 January 2025, subject to statutory conditions and the permitted 10% tolerance rule. Unternehmensserviceportal |
||||
| Albania | No | 20% | 0% | Annual turnover from 5 000 000 lek (40 000 EUR) |
| Andorra | No | 4,5% | 9,5%, 1%, 0% | Compulsory registration |
| Belgium | Yes | 21% | 12%, 6%, 0% | Mandatory registration, but for distance selling the threshold is 35,000 EUR |
| Bulgaria | Yes | 20% | 9%, 0% | Annual turnover from BGN 50,000 (EUR 25,500), but other thresholds for some activities |
| Bosnia and Herzegovina | No | 17% | 0% | Annual turnover from 50,000 convertible marks (27,000 EUR) |
|
United Kingdom | No | 20% | 5%, 0% | The compulsory VAT registration threshold is GBP 90,000 of taxable turnover over a rolling 12-month period. The United Kingdom left the European Union on 31 January 2020. Special rules continue to apply to certain transactions involving Northern Ireland under the relevant UK-EU arrangements. ГОВ.UK |
||||
| Hungary | Yes | 27% | 18%, 5%, 0% | Mandatory registration except for distance selling |
| Germany | Yes | 19% | 7%, 0% | Turnover for the previous year – from 17 500 EUR and expected turnover for the current year – from 50 000 EUR |
| Gibraltar | No | 0% | No | No |
| Greece | Yes | 24% | 13%, 6%, 0% | Annual turnover from 10 000 EUR |
| Denmark | Yes | 25% | 0% | Annual turnover from DKK 50,000 (EUR 6,700) |
| Ireland | Yes | 23% | 13,5%, 9%, 4,8%, 0% | Annual turnover of 75,000 EUR or more, of which 90 per cent is turnover from trading activities; otherwise the threshold for registration is 37,500 EUR |
| Iceland | No | 24% | 11%, 0% | Compulsory registration |
| Spain | Yes | 21% | 10%, 4%, 0% | Compulsory registration |
| Italy | Yes | 22% | 10%, 5%, 4%, 0% | Compulsory registration |
| Cyprus | Yes | 19% | 9%, 5%, 0% | Annual turnover from 15 600 EUR |
| Latvia | Yes | 21% | 12%, 5%, 0% | Annual turnover from 50 000 EUR |
| Lithuania | Yes | 21% | 9%, 5%, 0% | Annual turnover from 45 000 EUR |
| Liechtenstein | No | 8% | 3,8%, 2,5%, 0% | Annual turnover from 100,000 francs (86,700 EUR) |
| Luxembourg | Yes | 17% | 14%, 8%, 3%, 0% | Compulsory registration |
| Macedonia | No | 18% | No | Annual turnover from 1,000,000 denarii (16,600 EUR) |
| Malta | Yes | 18% | 7%, 5%, 0% | Compulsory registration |
| Moldavia | No | 20% | 8%, 0% | Annual turnover from 600 000 lei (30 300 EUR) |
| Netherlands | Yes | 21% | 6%, 0% | Compulsory registration |
| Norway | No | 25% | 15%, 12%, 0% | Annual turnover from NOK 50,000 (EUR 5,300) |
| Poland | Yes | 23% | 8%, 5%, 0% | Annual turnover from PLN 200,000 (EUR 46,700) |
| Portugal | Yes | 23% | 13%, 6%, 0% | Compulsory registration |
| Romania | Yes | 21% | 11%, 0% | Romania increased its standard VAT rate from 19% to 21%, effective from 1 August 2025. The principal reduced VAT rate is 11%, although transitional and special rules may apply to qualifying transactions. The domestic small business VAT exemption threshold is RON 395,000, subject to applicable registration requirements and exceptions. |
| Serbia | No | 20% | 10%, 0% | Annual turnover from 8,000,000 RSD (67,800 EUR) |
| Slovakia | Yes | 23% | 19%, 5%, 0% | The standard VAT rate increased to 23% on 1 January 2025. Reduced rates of 19% and 5% apply to specified goods and services. Mandatory domestic VAT registration generally arises when annual turnover exceeds EUR 50,000, with separate immediate registration consequences where turnover exceeds EUR 62,500 during the calendar year, subject to applicable statutory provisions. |
| Slovenia | Yes | 22% | 9,5%, 0% | Annual turnover from 50 000 EUR |
|
Finland | Yes | 25.5% | 13.5%, 10%, 0% | Finland increased its standard VAT rate from 24% to 25.5% on 1 September 2024. From 1 January 2026, the reduced VAT rate previously set at 14% was lowered to 13.5%. The annual turnover threshold for the small business VAT exemption is EUR 20,000, subject to applicable requirements and exceptions. vero.fi |
||||
| France | Yes | 20% | 10%, 5,5%, 2,1%, 0% | Compulsory registration |
| Croatia | Yes | 25% | 13%, 5%, 0% | Annual turnover from 230,000 kuna (31,200 EUR) |
| Montenegro | No | 19% | 7%, 0% | Annual turnover from 18 000 EUR |
| Czech Republic | Yes | 21% | 12%, 0% | The Czech Republic applies a standard VAT rate of 21% and a reduced rate of 12%, introduced on 1 January 2024. Since 1 January 2025, mandatory VAT registration has been determined by turnover during a calendar year, with thresholds of CZK 2,000,000 and CZK 2,536,500. The date on which VAT registration takes effect depends on which threshold is exceeded and the applicable statutory conditions. |
| Switzerland | No | 7,7% | 3,7%, 2,5%, 0% | Annual turnover from 100,000 francs (86,700 EUR) |
| Sweden | Yes | 25% | 12%, 6%, 0% | Compulsory registration |
|
Estonia | Yes | 24% | 13%, 9%, 0% | Estonia increased its standard VAT rate from 22% to 24%, effective from 1 July 2025. Reduced VAT rates of 13% and 9% apply to specified goods and services under the Estonian Value Added Tax Act. The domestic mandatory VAT registration threshold is generally EUR 40,000 of taxable turnover, subject to applicable exceptions and special registration requirements. Estonian Tax and Customs Board |
||||
Tax residence in Europe – expat taxes
Tax residency in a low-tax jurisdiction in Europe offers the opportunity to significantly reduce the fiscal burden. However, before choosing a country for residency, it is recommended to familiarise yourself with the current income tax rates in European countries.
The most favourable conditions for individuals are provided in the following European countries:
| European country | Peculiarities of income tax accrual | Standard rate of income tax |
| Andorra | Tax residents are taxed on all worldwide income. There are no taxes on wealth, gift, inheritance, capital gains (except for capital gains from buying and selling property in Andorra). Since 2015, a progressive system of taxation was introduced (some of the lowest taxes in Europe): Up to 24.000 EUR-0% (for non-residents 10%); 24,001 – 40,000 EUR – 5%; from 40,001 EUR – 10%. In the case of married couples, income tax is levied on amounts exceeding 40,000 EUR at a rate of 10%. The same tax is imposed on interest from bank deposits, but only for amounts over 3,000 EUR. Regarding the sale of real estate, capital gains are subject to tax at a rate of 15%, though every year the rate decreases, and from the 13th year of ownership, the property can be sold without fiscal obligations. | 10% |
| Bulgaria | The fiscal obligations due by Bulgarian tax residents extend to worldwide income. The uniform income tax rate recorded in the country is among the lowest throughout Europe, being no more than 10%. In addition to the income tax, Bulgaria applies state insurance contributions: social and health insurance: social insurance – 24.7-25.4%, of which 14.12-14.82% is to be paid by the employer, 10.58% by the employee; health insurance – 8%, of which 4.8% is to be covered by the employer, 3.2% by the employee. No capital gains tax exists, but there is a tax on property. This makes Bulgaria the lowest taxed country in Europe, due to its income tax of 10%. | 10% |
| Hungary | This European country levies an income tax rate of 15%. Hungary also enforces 13% for the social tax and 18.5% on the social security contribution. For this European country, the general rate for inheritance and gift tax is 18%, while it uses a favorable housing tax rate of 9%. It does not tax donations among direct relatives. | 15% |
| Gibraltar | Where the rate of income tax, of course depends on which system chosen. Surcharge or gross income, so in allowance system, tax is paid on income minus allowances and the rates are: first 4,000 pounds – 16%, next 12,000 pounds – 19%, after that-41%. Gross income system: first 10,000 pounds – 8%; next 7,000 pounds-22%; after that up to 25,000 pounds-30%. Then the tax rate for income over £25,000: the first £17,000 – 18%; next £8,000 – 21%, next £15,000 – 27%, next £65,000 – 30%, and anything over that – 27%. Payments for social security in Gibraltar are also imposed at a rate of 10% of the employee’s gross salary, minimum £12.10 and maximum £36.30 a week; 20% of the gross income of the employer, minimum £28.00 and maximum £50.00 a week; and a similar charge of 20% of a self-employed individual’s gross income, minimum £25.00 and maximum £50.00 a week. No such tax liability exists: a consumption tax such as VAT; a wealth tax; inheritance tax; death duty; tax on dividends; tax on gifts, and no social security contributions. It is to be noted that an income of £ 11,450 does not attract any income tax. Besides, the country also applies a variety of deductions that reduce the fiscal burden and create conditions for Gibraltar to retain its status of the territory with the lowest taxes in Europe for a long time to come. | between 8 per cent and 30 per cent |
| Cyprus | Cyprus introduced significant changes to its tax system effective from 1 January 2026. The standard corporate income tax rate increased from 12.5% to 15%, while the personal income tax-free threshold rose from EUR 19,500 to EUR 22,000.
The following progressive personal income tax rates apply from the 2026 tax year: EUR 0–22,000: 0% EUR 22,001–32,000: 20% EUR 32,001–42,000: 25% EUR 42,001–72,000: 30% Above EUR 72,000: 35% The tax reform also introduced changes to the Special Defence Contribution (SDC). The standard SDC rate on relevant dividend income arising from profits earned from 1 January 2026 was reduced from 17% to 5% for individuals subject to SDC, while separate transitional rules may apply to distributions of earlier profits. The SDC on rental income was abolished from the 2026 tax year. Qualifying Cyprus tax residents who are not domiciled in Cyprus may continue to benefit from exemptions from SDC on dividend and interest income, subject to the relevant statutory conditions. However, non-domiciled status does not provide a general exemption from all forms of income tax or taxation of rental income. Cyprus also maintains specific taxation rules and exemptions concerning capital gains, intellectual property and qualifying investment income. |
0 to 35% |
| Lithuania | In 2023, tax residents of Lithuania are subject to tax at a rate of 20% on income not exceeding 101,094 EUR per calendar year and 32% on everything exceeding this amount in respect of income from employment, payments to members of the management or supervisory board, income received under copyright contracts, received from the company that is also the employer of the given person, income under a civil law contract received by the manager of a small partnership not being its member. Dividends are also taxed at a rate of 15%, but the law provides for preferential treatment in respect of certain companies. There is no capital gains tax in this European country, there is no withholding of inheritance tax from close relatives, there is no gift tax or luxury tax. Social contribution of Lithuania amounts to 19.5%, including health insurance. | 20% to 32% |
| Liechtenstein | Liechtenstein has a very faithful, progressive income tax system, making the Principality practically the lowest in Europe. Annual income exempt from income tax includes: the income of a natural person is CHF 15,000, that of a single parent is CHF 22,500, and for a married couple, it is CHF 30,000. The highest income tax rate is 8%, imposed on income of more than CHF 200,000 per year for a single person, more than CHF 300,000 per year for a single parent, and more than CHF 400,000 per year for married couples. Still, one has to consider that this Principality in Europe has a communal tax represented by a surcharge ranging from 150% to 180% to the national income tax. The decision to increase the fiscal burden is made every year by the local government. Provided that there is a communal tax, the effective burden on personal income increases from 2.5% up to 22.4%. There are no inheritance, estate or gift taxes in Principality. On the contrary, there are capital gains tax – 3 – 24% depending on amount – and social contributions: 4.7% pension contribution, and 0.5% unemployment insurance. | 1 to 8 per cent |
| Slovakia | Current income tax rates: the tax base exceeding the subsistence minimum by 176.8 times (i.e. up to 38 553.01 EUR) is taxed at the rate of 19%, everything more – 25%; dividends – 7%; capital gains – 19%. There are no local taxes on personal income in this European country. | 19%/25% |
| Montenegro | Residents pay tax on worldwide income from any source, non-residents – only on income related to a permanent establishment in Montenegro, as well as on royalties, interest, and from the rental of local immovable property. From 1 January 2022, this European country has a progressive taxation scale: up to 700 EUR (gross) – no tax; from 701 to 1,000 – 9%; from 1,001 – 15%. Entrepreneurs pay tax at the following rates: from 8,400.01 to 12,000 EUR – 9%; from 12,000.01 EUR – 15%. A few years ago, the 9% income tax rate was the lowest in Europe, and the progressive scale leveled this advantage, but Montenegro continues to be an attractive jurisdiction for tax residency. | 9%/15% |
| Czech Republic | Since 2021, the Czech Republic has introduced a progressive taxation system for personal income: up to CZK 1,867,728 (~78,420 EUR) – 15%; anything above that – 23%. The income tax rate of 15% corresponds to the European average. | 15%/23% |
| Switzerland | In Switzerland, the income tax withholding is at three levels: federal, cantonal, and municipal. Federal income tax is progressive in the country, ranging between 0.77% and 11.5% above CHF 769,700. Still, each canton and municipality is entitled to its way of deriving the income tax rate from such a broad base. So in some parts of the country, taxes for the residents are not that high. This has resulted in an effective tax burden of 22.22 per cent on personal income in the Canton of Zug, 23.82 per cent in Appenzell-Innerrhoden, and 24.3 per cent in Obwalden, while in the Canton of Geneva, it reaches as high as 44.75 per cent. | from 22.22% |
| Estonia | As in most other European countries, in Estonia residents pay taxes on all income, while non-residents pay taxes only on profits earned in the country. The standard income tax rate is 20% | 20% |
How to obtain tax residency in Europe
In order to pay low taxes in Europe, it is necessary to obtain residency status in the desired country. In most cases, to become a tax resident, it is necessary to fulfil a number of conditions, including living in the country for at least 183 days during the year. However, it should be noted that in some countries the requirements are more stringent, and it is possible to obtain favourable tax residency in Europe even earlier.
| Country | Options for obtaining tax residency in Europe |
| Andorra | Residence exceeding 183 days in a year. Business centre in the country. |
| Bulgaria | In order to be considered a tax resident of Bulgaria, an individual must have a permanent address in the country and reside there for a minimum of 183 days within a 12-month period. Additionally, the individual must have a centre of vital interests in Bulgaria, such as a family, property, job, or business. |
| Hungary | Staying in Hungary for at least 183 days in a calendar year. |
| Gibraltar | A residence of at least 183 days in any tax year, and more than 300 days in the aggregate over three consecutive assessment years. |
| Cyprus | The minimum period that the house is available for is 183 days in aggregate. Please note that the day of departure is not counted as a day of residence, while the day of arrival is. Furthermore, if one arrives and departs in Cyprus, it would count as one day. The 60-day rule is applicable provided the following preconditions of the individual are met: does not reside in any other state for more than 183 days; is not a tax resident of other states; resides in Cyprus for more than 60 days; has economic interests (business, housing) in Cyprus. |
| Latvia | An individual may become a tax resident of this European country if they fulfil any of the following criteria: 1. They are registered as a resident in Latvia. 2. They have stayed in Latvia for more than 183 days in any 12-month period. |
| Lithuania | Please confirm whether the person concerned lived in this European country during the period indicated for taxation purposes, showing personal, social, or economic interests in Lithuania. The person has spent at least 183 days in Lithuania during the tax period. A person who has stayed in Lithuania for a period or periods that, when put together, amounts to more than 280 days in consecutive tax periods if the period of such stay totaled 90 days or more in any such tax period. Any natural person who is a Lithuanian citizen but does not correspond to the criteria stated above and who is paid under a labor contract or a contract which under its content corresponds to a labor contract, or whose expenses of residence abroad are covered from the State or municipal budget of the Republic of Lithuania. |
| Liechtenstein | Possession of a residence permit. Staying in the territory of the country for more than 6 months continuously, excluding short breaks. |
| Slovakia | Being physically present in Slovakia for 183 or more days in a calendar year |
| Montenegro | To qualify, individuals must: 1. Spend at least 183 days in Montenegro. 2. Have a permanent residence. 3. Have their centre of activity in Montenegro. |
| Czech Republic | Staying more than 183 days in a calendar year. Permanent residence in the Czech Republic (permanent address). |
| Switzerland | By Swiss domestic tax legislation, an individual is deemed a tax resident if they: 1. Have a permanent place of residence and a center of vital interest in Switzerland. 2. Intend to engage in gainful activity in Switzerland for a consecutive period (excluding short-term absences) of at least 30 days. 3. Intend to remain in Switzerland without engaging in gainful activity for a consecutive period (excluding short-term absences) of at least 90 days. |
| Estonia | If the stay in Estonia in any 12-month period exceeds 183 days |
It is quite difficult to choose on your own the country in Europe which offers the best tax residency, as you are bound to study the corporate and tax legislation of the country you are interested in rather thoroughly. So, it would be far easier to ask for help from lawyers and tax consultants operating in Regulated United Europe.
Accordingly, Regulated United Europe lawyers would recommend considering the following criteria when choosing a country to start a business:
Facility of starting and operating a business. In addition to the tax rate, remote management of the company is a concern, as well as how much it would cost to maintain. If your area of business requires licenses or permits from the state, you will want to carefully consider this issue before opening a company.
Taxation. The main issue for both you and your company as owners are individuals depends on whether you plan to reside in the country where you open your business or only intend to set up a legal entity and manage it remotely. In the first case, taxation for individuals is important for you; in the second case, it is only corporate taxes.
Human capital. The list of countries that would fit the bill can vary greatly depending on the business of the company – if you need a highly qualified labour force with good English language skills to carry out your activities, then the countries with the lowest wages in the EU are not the right option for you.
Level of salary. As in the point above, the most important role is taken by the area of the company’s activity – if the area of your business presupposes employment of a large number of low-skilled labour, you should first refer to the countries with the lowest wages of the European Union.
Countries in Europe that have the lowest tax
The Estonian model of taxation is unique among European countries, probably the most favorable for entrepreneurs and investors; it presupposes nondistortion of the process by taxing only the profit distribution, and it can be said to have obvious advantages in business growth and development. In the present paper, we would like to discuss Estonia as a leader among European countries providing the most favorable conditions to companies in respect of taxation.
Characteristics of the Estonian Tax System
The Estonian taxation system stands apart from all other countries by its corporate profits, which are only taxed in instances of distribution of the profit. Profits invested or reinvested in the company are not taxed, thereby encouraging reinvestment and rapid enterprise growth. It encourages companies to grow and develop innovative activities while it is now becoming one of the most promising jurisdictions for doing business in Europe.
Benefits of Estonian tax model for business
- Encouraging reinvestment. Since it does not provide for tax on retained profit, companies effectively can boost their capital with reinvestments. This is one of the main driving forces behind sustainable growth.
- Transparency and simplicity: The Estonian tax system is characterized by a high degree of transparency and simplicity. All this decreases administrative barriers and compliance costs.
- International business support. Due to Estonia’s well-developed digital infrastructure and the possibility to manage business online with the help of its unique system called e-Residency, many favorable conditions are created for international companies to be happy with their decision to choose this country as a destination for their endeavors.
- Tax incentives for a startup company. Having provided a number of tax incentives and support for the establishment of start-ups, it is actually one of the best platforms in Europe for innovative entrepreneurship.
It forms a leader in Europe on the Estonian scene regarding favourable taxation for business. A special Estonian tax system encouraging reinvestment and innovation, transparency, and ease of administration, together with strong support for international and innovative businesses, form an ideal environment for a company to develop and expand its business in Estonia. All these factors turn the country into an attractive point on the European map for entrepreneurs who try to find the maximum of efficiency in their business and look for a tax structure that would be optimal.
Lowest Income Taxes in Europe
Excluding the search for optimal conditions to work and live in, Europe represents a mosaic of diverse tax systems. It is among European states that Estonia became an outsider for its tax policy, offering some of the most favorable conditions for citizens. Below follows a closer look at why it is Estonia leading in Europe regarding favorable personal income taxation.
Peculiarities of Income Tax in Estonia
Estonia applies a flat personal income tax rate of 22% in 2026. Unlike countries with progressive personal income tax brackets, Estonia generally taxes personal income at a uniform statutory rate, subject to applicable exemptions and deductions.
From 1 January 2026, the general basic tax-free allowance is EUR 700 per month, equivalent to EUR 8,400 annually, and no longer decreases as an individual’s income increases. Different allowances may apply to individuals who have reached the relevant pension age.
Employment income may also be subject to unemployment insurance contributions, mandatory funded pension contributions and employer-paid social tax. Consequently, the effective tax burden on employment cannot be determined solely by reference to the 22% personal income tax rate.
Estonian Tax and Customs Board
Strengths of Estonian tax environment
- Understandability and transparency. The Estonian tax system has a high degree of comprehensibility and transparency. Ease of declaring and payment decreases the administrative burden on taxpayers.
- Tax benefits and deductions. Speaking about the individual taxpayers, Estonia provides quite a wide range of tax-free allowance and deductions that significantly reduce the taxable income and thus the amount of tax payable.
- Incentivizing investments: Due to the Estonian tax system’s peculiarity, there is no taxation levied on reinvested profit, which would encourage investments and is one way of benefiting capital growth.
- Digitalization of processes: Estonia is considered a leader in the world in digitalizing public services, including tax administration. It provides for electronic income declaration to simplify this process as much as possible.
While most European states put noticeably higher income tax rates and at the same time have more complicated taxation and administration systems, Estonia creates more attractive conditions for people. This not only reduces the financial burden on taxpayers but also provides favorable conditions to attract highly qualified specialists and investors in the country.
Estonia is proof that even within the frames of the modern European economy, it is possible to create a tax system that would favor business development and attract foreign specialists. The combination of low tax rates with simplicity and transparency of taxation makes Estonia one of the most attractive countries in Europe for living and working. Thus, Estonia is the leader in terms of favourable personal income taxation not only throughout Europe but also can be viewed as a successful example for many countries on the international level.
Lowest taxes in Europe for business
Nowadays, a country may be chosen based on its tax policy for business implementation. Europe with different tax systems gives an entrepreneur numerous opportunities to optimize his or her tax liabilities. In this context, Estonia belongs to those countries which have some of the most favorable tax systems in Europe for business by offering special conditions for developing companies and attracting investments.
Peculiarities of the Estonian tax system
Estonia operates a deferred corporate income tax system under which retained and reinvested profits are generally not subject to corporate income tax until they are distributed. As of 2026, the standard corporate income tax rate is 22/78 of the net distribution, equivalent to 22% of the gross profit.
Corporate income tax applies not only to dividends but also to certain other taxable payments, including non-business expenses, fringe benefits, gifts, donations and hidden profit distributions. Therefore, an Estonian company may incur corporate income tax liabilities even without formally distributing dividends.
The taxation of profits at the distribution stage allows businesses to retain and reinvest earnings without immediate corporate income taxation, subject to applicable national and international tax legislation.
Estonian Tax and Customs Board
Business advantages
- Incentivising reinvestment: due to the fact that the system defers taxation of the profits to the moment of their distribution, it encourages companies to reinvest their earnings in business and accelerates development and expansion.
- Simplicity and transparency: high simplicity and transparency are typical for the Estonian tax system, which decreases the administrative burden of a company and the risk of tax disputes.
- Support for innovation: Estonia actively supports innovative projects and startups by offering tax incentives and several support programmes for them, which turns the country attractive for technology companies.
- Digital economy. Thanks to the developed e-government infrastructure, Estonia offers unique opportunities to conduct business in a digital environment, making a lot of procedures easier and more accessible.
Comparison with other European countries
Among other European countries that have more traditional and often heavy approaches to taxation, Estonia has some undeniable advantages in doing business. This places Estonia among the top destinations for investors and businesses looking for a spot to invest in with regard to effective tax planning and optimization of liabilities.
Estonia is among the most striking European countries when it comes to attracting attention in terms of taxation with regard to entrepreneurs. The innovative approach to taxation, support for reinvestment, ease of administration, and focus on digitalization create a very favorable environment for the development of companies of all sizes. Thus, Estonia guarantees not only some of the lowest taxes in Europe for businesses but also it is a prime example of how state tax policy can drive economic growth and innovation.
Lowest taxes for freelancers in Europe
In the globalised world and in the development of the digital economy, freelancing is turning into one of the most popular forms of employment. Europe, with its diverse tax systems, offers freelancers ample opportunities. On the other hand, when choosing a country to register an activity, it is important to take into account not only the amount of taxes but also the convenience of doing business. In this context, Estonia is the most attractive jurisdiction for freelancers due to its favourable tax policy and developed e-government infrastructure.
Peculiarities of taxation of freelancers in Estonia
Estonia’s e-Residency programme provides foreign entrepreneurs with a government-issued digital identity that enables access to selected Estonian electronic services, including company establishment, digital document signing and online business administration.
However, e-Residency does not constitute personal tax residency, grant a residence permit or automatically provide tax advantages. Individuals conducting freelance activities through an Estonian company may remain subject to personal income tax and social security obligations in their country of residence.
An Estonian company established by an e-resident is generally an Estonian tax resident, but its activities may create additional corporate tax obligations abroad, particularly where the company is effectively managed or operates through a permanent establishment in another country.
The standard Estonian personal income tax rate in 2026 is 22%, while corporate distributions are generally taxed at 22/78 of the net distribution.
Benefits for freelancers
- Simplicity and accessibility. Registering and managing a business is as easy and accessible through e-Residency as anywhere in the world for freelancers from different corners of the world.
- Tax optimisation. The Estonian tax system is very friendly, enabling possibilities of tax optimization, including several exemptions and deductions applicable to the income of freelancers.
- Government support. The Estonian government does much to support freelancers and entrepreneurs by offering various support and training programs.
- Digital infrastructure. Thanks to a highly developed digital infrastructure, freelancers can efficiently manage their business, communicate with clients and access government services online.
Comparison with other European countries
Compared to other European countries, Estonia offers some of the most favourable conditions for freelancers. Low tax rate, possibility of tax optimisation, as well as convenience and ease of doing business make Estonia an attractive jurisdiction for international freelancers.
Choosing Estonia as a jurisdiction at the time of registration of a freelancer’s activity opens not only possibilities for optimization of tax liabilities but also access to the most convenient and effective system for carrying out business management. The benefits of the Estonian tax system, together with the developed digital infrastructure of this country, turn it into one of the most attractive countries in Europe for freelancers who seek to maximize efficiency and minimize administrative barriers when running their business.
Which EU country is best to choose for tax residence
Choosing a country of tax residence is one of the most important decisions that every international entrepreneur and investor needs to make. Within the European Union, there are numerous jurisdictions with their own certain tax regime which offers different advantages. However, when it comes to choosing tax residency, it is not only a question of the tax rate but also of the general policy of taxes, stability of the economic environment, and ease of doing business. In this context, Estonia is one of the most attractive countries for tax residency in the EU.
Main advantages of Estonia
- Progressive taxation exists. Estonian corporate income tax can be paid only in one case: when an enterprise distributes dividends. Thus, companies can reinvest their profits without additional tax burdens on them or their owners.
- Simplicity and transparency are in place. The Estonian tax system is characterized by a high level of transparency and predictability, which minimizes risks for businesses and eases the planning of tax liabilities in general.
- Digital economy and e-Residency. Estonia is one of the most advanced countries in the world in terms of the digitalisation of public services. The e-Residency programme provides an opportunity to run the businesses online from anywhere in the world, which is especially appealing for international entrepreneurship.
Comparing to Other EU Countries
While Other EU countries—Ireland or Cyprus, for example—offer attractive tax regimes for businesses, this is an unbeatable combination in Estonia: low taxes, digitization of processes, and stability in the business climate. The Estonian tax environment is simple and clear-cut, unlike other jurisdictions where low taxes are combined with complex administration or uncertain tax laws.
Estonia offers a developed digital business infrastructure and a corporate tax system that generally defers taxation of retained profits until distribution. However, incorporating an Estonian company or obtaining e-Residency does not automatically make an entrepreneur an Estonian personal tax resident.
Individual tax residency is determined under the Estonian Income Tax Act and applicable international tax treaties. A person may qualify as an Estonian tax resident based on their place of residence or physical presence in Estonia for at least 183 days over 12 consecutive calendar months, subject to the relevant legal rules.
Entrepreneurs managing Estonian companies from abroad must also consider potential tax liabilities in other jurisdictions, including permanent establishment rules, place of effective management and applicable double taxation agreements.
EU countries with the lowest import taxes
Import duties are among the most important trade policy tools that influence economic relationships among countries. Inside the EU, tariffs and duties are harmonized for all members of the customs union, but due to numerous trade agreements and economic zones, some countries and territories offer special conditions when importing goods. In this article, we will look at which EU countries can boast the lowest import duties and what benefits this can provide to international entrepreneurs.
EU and Import Duties: The Big Picture
The European Union levies the Common Tariff Rate on goods imported from outside of the union. However, through various trade treaties, items originating from specific countries can be imported at lower rates or even duty-free. Within the EU itself, there are free economic zones and territories with special taxation regimes that may also offer lucrative conditions for imports.
Countries with the Most Favorable Conditions
- The Netherlands. Having a favorable geographical position, together with the port in Rotterdam as one of the biggest in the world, creates optimal conditions in the Netherlands for importing and further re-export. The state actively uses its logistical advantages by offering customs clearance with the simplified procedure and special economic zones.
- Belgium. Belgium also enjoys the same logistical advantage because of its port, housed in Antwerp. There, customs are known to be quite efficient, and the channels of accelerated import processing are well developed.
- Luxembourg. This country doesn’t have any seaports, but still it offers lots of attractive conditions for imports due to very favorable tax legislation and a high level of logistics infrastructure development.
- Malta. Malta provides special conditions in case of importation of goods, especially for the services and technology sector, by view of policy to attract foreign investment and develop economy.
EU trade agreements with third countries ensure low import duties for European businesses. Where these agreements are between the countries participating, a substantially reduced rate or even complete waiver from duty may be extended to specific categories of goods.
Which country to choose for importation of goods into the European Union depends on many factors, including logistics and customs procedures, as well as tax policy. For instance, the Netherlands, Belgium, Luxembourg, and Malta can be included in the category of attractive jurisdictions in terms of import duty and may provide substantial benefits for international entrepreneurs. However, while choosing a tax strategy, a holistic approach has to be considered by analyzing all the associated costs and likely benefits of trading in the country selected.
Tax comparison Europe
Tax policies vary widely across Europe, making the continent attractive to international investors in certain jurisdictions depending on their tax rates and regulatory environment. In this article, we will look at the countries with the highest and lowest tax rates in Europe to help investors and entrepreneurs make informed choices when planning their business operations.
High-tax countries
- Denmark. Denmark is often singled out as having one of the highest levels of taxation in the world. The standard income tax rate for individuals can reach up to 55.9%, including all municipal and state levies. This is due to the high level of social guarantees and quality of life.
- Sweden. Sweden’s taxes are also high, with a top personal income tax rate of about 52 per cent. As in Denmark, high taxes go to finance extensive social protection and public services.
- Belgium. Belgium has one of the highest taxation rates in the EU, with a top personal income tax rate of up to 50%. The tax system in Belgium is complex, with many local and regional taxes increasing the overall tax burden.
Low-tax countries
- Bulgaria. Bulgaria applies a standard corporate income tax rate of 10% and a flat personal income tax rate of 10% to most categories of taxable personal income. However, businesses and individuals must also consider social security contributions, dividend taxation, VAT and other applicable taxes. The overall effective tax burden depends on the nature of the business activities and the taxpayer’s circumstances.
- Ireland. Ireland applies a corporate income tax rate of 12.5% to qualifying trading income and 25% to most non-trading income. Large multinational and domestic groups within the scope of the OECD Pillar Two rules are subject to a minimum effective tax rate of 15%, calculated according to the applicable legislation. Ireland remains an established jurisdiction for international corporate operations, particularly in the technology and financial services sectors.
- Cyprus. Cyprus increased its standard corporate income tax rate from 12.5% to 15% on 1 January 2026. The country continues to offer tax incentives, including the intellectual property box regime, participation exemptions and specific benefits for qualifying non-domiciled tax residents. Eligibility for tax relief depends on the applicable legal requirements, economic substance and the characteristics of the income concerned.
The choice of a country to do business in Europe depends significantly on the tax policy and economic environment. High-tax jurisdictions tend to offer high levels of social protection and developed infrastructure, while low-tax jurisdictions attract businesses with favourable tax rates and less bureaucracy. It is important to carefully analyse all aspects before deciding where to incorporate a company to ensure the best fit between tax strategy and business objectives.
Taxes optimization in Europe
A study conducted by Organisation for Economic Co-operation and Development bears witness that corporate taxes are the most destructive to economic growth in Europe, whereas personal income tax and consumption tax are less destructive. The same goes with property taxes: they have the least contribution to deterring a country’s economic growth. The competitive and neutral tax code contributes to the country’s sustainable economic growth and attracts foreign investment, and simultaneously collects sufficient funds in the treasury for state needs.
The Estonian tax rating is most attractive in Europe already for the tenth year. First, the 20 per cent corporate income tax rate is paid only by distributed profits. Second, Estonia boasts a flat 20 per cent personal income tax rate not applied to personal dividend income. Third, property tax applies only to the value of land but not to real estate or capital. Finally, the country has a territorial tax system that excludes from its domestic tax 100% of foreign profits earned by domestic corporations.
International Tax Competitiveness Index 2026
According to the Tax Foundation’s International Tax Competitiveness Index 2026, the five highest-ranked jurisdictions were:
Estonia
Latvia
New Zealand
Switzerland
Lithuania
Among European OECD countries, Estonia ranked first, followed by Latvia, Switzerland, Lithuania and Luxembourg.
The index evaluates tax systems based on corporate taxation, individual income taxation, consumption taxes, property taxes and cross-border tax rules. Its rankings measure tax competitiveness and neutrality rather than identifying the countries with the lowest overall tax burden for every individual or business.
Overview of best ranking EU countries regarding tax competitiveness
 Estonia
- For one decade now, Estonia has been ranked number 1 in the International Tax Competitiveness Index.
- There is only tax on distributed profits under the Estonia corporate income tax system, and thus companies can reinvest their profit without paying any taxes.
- Property taxes are only levied on the value of the land.
Switzerland
 Switzerland
- Switzerland has above-average reimbursement conditions for investment in machinery, buildings, and intangible assets.
- Switzerland boasts 102 tax treaties, which is quite an impressive number, and no CFC (controlled foreign corporations) rules – the latter are designed to block corporations from shifting pre-tax profits from a high-tax country to a low-tax country by utilizing forms of income that can be easily shifted round.
Czech Republic
 Czech Republic
- The Czech Republic applies a standard corporate income tax rate of 21%, effective from the 2024 tax year. The previous standard rate of 19% no longer applies to ordinary corporate profits. Certain qualifying investment funds are subject to a reduced rate of 5%, while specific pension-related funds may qualify for a 0% rate. The tax treatment of dividends, capital gains and foreign-source income depends on applicable participation exemptions, double taxation treaties and statutory conditions.
Finanční správa
- High threshold for obtaining a VAT number.
- The Czech Republic also has a territorial tax system that only exempts both dividends and capital gains earned from other European countries, and also has an extensive network of tax treaties.
 Luxembourg
- Luxembourg does not provide a general capital gains tax exemption for all assets held for at least six months. The taxation of capital gains depends on the type of asset, the taxpayer’s residence status, the size of the ownership interest and the applicable statutory provisions.
For Luxembourg-resident individuals, gains from the disposal of certain movable assets held for more than six months may be exempt from income tax, provided that the relevant conditions are satisfied. However, gains arising from substantial shareholdings, real estate and certain other assets may remain taxable under separate rules.
Corporate taxpayers are generally subject to capital gains taxation unless a specific exemption applies, such as the participation exemption available for qualifying shareholdings. The six-month holding period should therefore not be presented as a universal exemption applicable to all investments.
 Lithuania
 Lithuania
- Lithuania applies a standard corporate income tax rate of 17% from 1 January 2026, following an increase from 16% in 2025. Qualifying small companies with annual revenue not exceeding EUR 300,000 may benefit from a 0% corporate income tax rate during their first two tax periods and a reduced rate of 7% in subsequent periods, subject to the applicable statutory requirements and restrictions. Special tax treatment may also be available for qualifying research and development activities and other eligible income.
finmin.lrv.lt
- Labour taxes are lower than the average in the EU.
Least competitive tax systems in Europe
Italy has the second least competitive tax system in the OECD. The Italian tax system includes a number of distortionary property taxes, such as: i) a separate levies on the sale of real estate; ii) other real estate financial transactions; and iii) a wealth tax on individual assets. The high standard VAT rate of 22 per cent is complemented by one of the fifth narrowest consumption tax bases in the OECD.
The economies that rank with Italy at the bottom of the European tax competitiveness ranking – France, Portugal, Poland, and Spain – commonly impose relatively high marginal corporate income tax rates or have multiple layers of tax rules. All five countries that are ranked at the bottom have aggregate corporate tax rates above the EU average.
Ireland ranks poorly in the ranking despite a relatively low corporate tax rate. This is due to the high level of personal income and dividend taxation, but also because of the relatively narrow VAT base. The five lowest ranked countries have abnormally high corporate income tax rates in a range from 25.825 per cent up to 35 per cent. Unusually high top income tax thresholds well above average income are found for four of the five lowest-ranked countries. Of these, the highest aggregate corporate income tax rate is 31.5 per cent in Portugal. Portugal also levies one of the highest top personal income tax rates at 53% in addition to further taxes.
Corporate income tax systems differ significantly across OECD countries. Hungary applies a standard national corporate income tax rate of 9%, although local business tax and other obligations may increase the effective tax burden. Ireland applies a rate of 12.5% to qualifying trading income and 25% to most non-trading income, while qualifying large corporate groups are subject to the global minimum taxation framework.
Lithuania increased its standard corporate income tax rate to 17% from 1 January 2026, with reduced rates available for eligible small businesses and certain qualifying activities.
Estonia does levy corporate income tax, but generally defers taxation of retained profits until distribution. In 2026, distributed profits are subject to a corporate income tax rate of 22/78 of the net distribution. The statement that Estonia does not impose corporate income tax is therefore legally incorrect.
Loss relief rules: carry forwards and carry backs
Hungary, Poland and Slovakia have the most severe restrictions on the carry-forward of company losses (next year): carry-forwards are not allowed and carry-forwards are not only limited to five years, but also limited to 50 per cent of taxable income. In 2023, only the Estonian and the Latvian systems consciously have no limits on loss carryforwards.
Capital allowance: machinery, buildings and intangible assets
For instance, Estonia and Latvia permit 100 per cent of the present value of capital investments to be written off, since their corporate tax applies only to distributed profits and thus is determined by cash flow.
Portugal, Luxembourg, Germany and France apply income tax to all or part of their corporate income tax base.
Most countries tax personal income using two approaches. First, countries impose income taxes and payroll taxes on income from work. The structure of those taxes can affect people’s choices of whether to work, to work additional part-time jobs, or whether a second family breadwinner will work. Second, people are taxed on their savings through the imposition of taxes on capital gains and dividends. In most cases, these taxes represent a second tier of corporate income taxes and could have an impact on savings and investment decisions. High capital gains and dividend taxes may lower the total savings and investments in a country.
The income tax system in most countries has a progressive tax structure where earn more income, they fall into a higher tax bracket. The top statutory personal income tax rate applies to all income above a cut-off level.
The total statutory personal income tax rate including employee social contributions is highest in Slovenia at 67.5 per cent while Estonia has the lowest rate at 21.6 per cent.
Along with wage income, individual income tax systems in a large number of countries tax investment income through the taxation of capital gains and dividends.
Capital gains generally arise when an individual purchases an asset – usually corporate stock – in one period and then sells it in another period at a gain. A dividend is an after-tax payment to the individual from corporate profits.
Capital gains taxes and personal dividend taxes represent a double taxation of corporate profits and thereby further increase the tax burden on capital. When a corporation realizes a profit, it first faces the corporate income tax. The after-tax profit can then typically go one of two ways. The corporation can retain the after-tax profit. That raises the value of the business and thereby its stock price. The shareholders then sell the stock and receive capital gains, which requires them to pay tax on that gain. Another option is that a corporation distributes after-tax profits to shareholders through dividends. Shareholders who receive dividends then pay dividend tax on that income.
Example:
If a company earns $1 million of taxable income with a 20 per cent corporate income tax rate, there would remain $800,000 to reinvest in the company, thereby increasing the value of the stock, or to pay dividends. The shareholder may then be subject to an additional 20 per cent tax on the gain from the sale of the stock or on the company’s dividends. In effect, the system taxes business profits at 36 percent. An individual who expects that an investment will yield a 10 percent real return may realize a mere 6.4 percent profit after tax.
VAT/sales tax exemption threshold
Most OECD countries offer thresholds above which firms must pay VAT/sales tax. Where a firm’s annual income is beneath the threshold, it is not obligated to enter the VAT system. This means that small businesses – contrary to those above the threshold – do not charge VAT on commodities sold to final consumers, but at the same time cannot recover a VAT refund on the amount paid for business expenses. While relieving very small businesses from the burden of the tax saves administrative and compliance costs, needlessly high thresholds are distorting in that they tend to benefit small enterprises at the expense of larger firms.
Property tax
Property taxes are government imposition on an individual’s or entity’s assets or estates. The collections and frequency depend on the class of estate tax. Inheritance tax for instance is imposed once a person dies and his or her estate flows into the hands of heir correspondingly. Estate taxes come in fixed periods, which for most countries is annually, and their assessment has been dependent on the value of assessable property such as land and real estate. Apart from land tax the rest of the estate taxes augment economic distortions and bring adverse long-run impact on economy and its productivity.
Property taxes
Many countries also impose estate taxes on a person’s wealth. These come as inheritance or succession taxes, which are imposed either on a person’s estate at death or on assets transferred from the deceased’s estate to the heirs, or as a recurring tax on a person’s wealth. Inheritance and inheritance taxes restrict resources available for investment or production and decrease incentives to save and invest. This decrease in investment goes against economic growth. Additionally, these taxes – especially inheritance and inheritance tax – can be avoided through certain planning techniques, making the tax an inefficient and unnecessarily complex source of government revenue.
Inheritance and gift taxes are significant burdens on the taxpayer, while at the same time producing very scant revenues for the state. Inheritance, inheritance and gift taxes in OECD countries generated an average of 0.15 per cent of GDP in tax revenue, with the highest amount collected only 0.74 per cent of GDP in France, despite the fact that this tax may go as high as 60 per cent in some cases.
European countries with no inheritance, inheritance or gift tax: Austria, Estonia, Israel, Latvia, Norway, Slovakia and Sweden.
Property transfer taxes
Property transfer taxes are taxes on the transfer of real estate, land improvements, machinery from one person or company to another. In the Czech Republic, Estonia, Lithuania and Slovakia there are no property transfer taxes.
Withholding taxes on dividends, interest and royalties to foreign investors
The withholding rates are the highest in Switzerland, which withholds 35 per cent on dividend or interest payments by Swiss companies to foreign entities or individuals. The taxation of dividends and interest income differs between Estonia, Hungary and Latvia and depends on the recipient’s status, the source of income and applicable national legislation.
In Estonia, distributed corporate profits are generally taxed at the company level at 22/78 of the net distribution. Dividends paid from profits taxed at the standard corporate rate are generally not subject to additional Estonian withholding tax, although special transitional rules apply to certain previously taxed distributions.
In Hungary, dividends and interest received by individuals may be subject to personal income tax and, in certain circumstances, social contribution tax. Exemptions and preferential treatment may apply depending on the recipient and the type of income.
Latvia also operates a distributed-profit corporate tax system, under which dividend distributions are generally subject to corporate income taxation. The treatment of dividends and interest received by individuals or non-resident entities depends on applicable domestic provisions and double taxation agreements.
Therefore, it is inaccurate to state that dividends and interest are universally exempt from taxation in these three countries.
Estonian Tax and Customs Board
Royalties – On royalties also, Belgium calls for firms to withhold the maximum amount, 30 per cent. Withholding tax on royalties paid to non-residents varies significantly between European jurisdictions. Some countries provide exemptions for qualifying royalty payments, while others impose withholding tax under domestic legislation, subject to reductions or exemptions available under double taxation agreements or EU directives.
Within the European Union, Council Directive 2003/49/EC (the Interest and Royalties Directive) may provide an exemption from withholding tax on qualifying cross-border interest and royalty payments between associated companies established in different Member States, provided that the statutory requirements are satisfied.
However, the absence of withholding tax cannot be assumed for every royalty payment made from Hungary, Latvia, Luxembourg, the Netherlands, Norway, Sweden or Switzerland. The applicable treatment must be determined by reference to the payer’s jurisdiction, the recipient’s tax residence, beneficial ownership, the nature of the intellectual property rights and relevant treaty provisions.
Also, lawyers from Regulated United Europe provide legal services for obtaining a
crypto license in Europe
.
Why Regulated United Europe?
Regulated United Europe OÜ (RUE) is a European legal consulting firm specializing in financial licensing, company formation, and regulatory compliance. Since 2016, we have helped hundreds of businesses obtain crypto, gambling, forex, and EMI/PSP licenses across 35+ jurisdictions.
With offices in four EU countries and a team of experienced lawyers, we provide end-to-end support — from initial consultation and company registration to license acquisition and ongoing compliance management.
500+
Clients Served
35+
Jurisdictions
Since 2016
Years in Business
4
EU Offices
Registered European Legal Consultancy
Regulated United Europe OÜ is a company registered in Estonia that provides legal and regulatory consulting services, including company formation, financial services licensing support and corporate compliance advisory services.
Where a particular matter requires representation by a locally admitted advocate or another regulated legal professional, RUE may cooperate with appropriately qualified independent lawyers and professional partners in the relevant jurisdiction.
Company registration must not be confused with authorisation to practise law as a regulated advocate or law firm.
Any claim concerning professional legal practice authorisation should identify the relevant licensed individual or legal entity and the competent professional regulatory authority.
Multilingual Team
Our experts speak English, German, Russian, Chinese, and 12+ other languages for global client support.
Turnkey Solutions
From company registration to license acquisition and compliance — we handle the entire process end-to-end.
Dedicated Support
Personal consultant assigned to each client. Direct communication channels, no call centers.


